Monday, November 2, 2026

What the 2027 FedNow Discount Program Means to Credit Unions

 For credit unions that have been considering FedNow but have yet to move forward, the Federal Reserve has added a significant financial incentive to the equation. Under the Federal Reserve’s 2027 FedNow Service Discount Program, qualifying financial institutions can receive statement credits for enabling FedNow receive and send capabilities.

For credit unions that have been considering FedNow but have yet to move forward, the Federal Reserve has added a significant financial incentive to the equation. Under the Federal Reserve’s 2027 FedNow Service Discount Program, qualifying financial institutions can receive statement credits for enabling FedNow receive and send capabilities.

Depending on an institution’s FedACH Receipt Discount Program status and FedNow send volume, those incentives can total as much as $100,000.

That creates a meaningful opportunity for credit unions. An investment in instant payments that may already be on the technology roadmap could now come with financial incentives that offset a portion of the implementation cost.

However, the amount available to each credit union will depend on several factors, including its FedACH Receipt Discount Program status and FedNow send volume. The structure of the program makes an important distinction between simply connecting to FedNow and actually using it. The largest incentives are associated with send capabilities and transaction volume. 

For credit unions, that means planning for 2027 should include not only how to enable FedNow, but also how members and businesses will use it.

Making sense of that distinction starts with the incentives themselves.

Understanding the Incentives

According to the Federal Reserve’s published 2027 FedNow Discount Program, institutions may qualify for a receive discount, a send discount or both.

On the receive side, an institution with FedNow receive enabled may qualify for a maximum $5,000 statement credit. That increases to $10,000 for institutions eligible for the FedACH Receipt Discount Program and $20,000 for institutions participating in that program. Receive qualification also requires participation in certain Federal Reserve Financial Services, including the Exception Resolution Service, FedPayments Insight Service and either a premier FedDetect Anomaly Notification Service subscription or API integration of a qualifying pre-transaction fraud mitigation service, all active for at least six months.

The potential incentive becomes substantially larger with send. An institution with FedNow send enabled can qualify for a maximum $20,000 discount by reaching at least 100 completed qualifying send transactions per month. Institutions eligible for the FedACH Receipt Discount Program can qualify for up to $40,000 by reaching at least 2,500 transactions per month, and participants in that program for as much as $80,000 at the same threshold.

Existing FedNow senders already at or above the applicable threshold have another path, which includes increasing their average monthly send volume by at least 50%.

The Federal Reserve provides complete requirements in its FedNow Service 2027 Discount Program. 

Determine What Your Credit Union Can Actually Qualify For

The possibility of $100,000 is attention-grabbing, but it will not apply to every credit union. The higher incentives are connected to eligibility for or participation in the separate FedACH Receipt Discount Program, under which participants must receive at least one million items per month through FedACH and qualify as a Premium Receiver. The Federal Reserve outlines those requirements separately.

Before incorporating the FedNow incentive into a technology budget or business case, credit unions should therefore confirm which receive and send tiers apply, calculate the potential credit and compare it with implementation costs. Once the applicable tiers are clear, the next question is how far to go.

Do Not Treat Receive as the Finish Line

Receive is an important starting point, allowing a credit union to accept instant payments for its members and establishing participation in the network. Receive alone, however, does not let members initiate an instant payment; only send does that.

That distinction matters strategically, and the incentive structure reflects it. The maximum send credit is four times the maximum receive credit, and unlike receive, the send incentive requires transaction activity. The question for credit unions therefore extends beyond “How do we connect?” to “What will our members send?” That conversation must happen before implementation, and it begins with the transactions themselves.

Identify the Transactions Before Projecting the Volume

Credit unions should identify specific member and business use cases that could reasonably generate send transactions. Those will differ by institution and membership base, and could include account-to-account transfers, loan proceeds, business disbursements, supplier payments or other transactions where immediate settlement creates tangible value.

With use cases identified, credit unions can estimate potential volume. That matters most for institutions targeting the larger send discounts. A 2,500-transaction monthly requirement translates into roughly 83 transactions per day, which leads to the question, “Does the credit union have enough members, businesses and applicable use cases to generate that activity? And if not, what would need to change?” The answer could influence everything from which use cases are prioritized to how the capability is introduced to members.

Volume, in turn, must be built within a defined window, which makes timing the next consideration.

Work Backward from the Qualification Period

Under the Federal Reserve’s published terms, institutions must meet the applicable send volume requirement for six qualifying months within the calendar year or six months following opt-in, whichever is longer. Those months do not have to be consecutive.

The send statement credit is also divided into two parts. Fifty percent is applied upon opt-in, with the remaining 50% applied after the volume requirements have been met. If the requirements are not ultimately satisfied, the initial credit may be reversed.

That makes the implementation timeline important. A credit union that waits until late in the year to evaluate send capabilities, integrations, use cases and member adoption could leave itself little room to build qualifying volume. Planning should begin well before the expected go-live date.

All of this planning, however, should serve a larger purpose than the credit itself.

Use the Incentive to Strengthen the Business Case

The 2027 program works best as one input into a larger instant payments strategy. A credit union should not implement FedNow simply because a statement credit is available. 

Instead, the incentive belongs within a broader business case for capabilities the institution expects to use well beyond 2027, one that weighs technology requirements, operational readiness, fraud controls, member demand, use cases and projected volume alongside implementation costs.

If that analysis already supports moving forward, the Federal Reserve’s program makes the timing considerably more attractive. The statement credits will expire long before the value of instant payments does. For credit unions that have kept FedNow on the roadmap, 2027 offers a chance to offset part of the investment while putting long-term capabilities in place, and the time to find out whether your credit union qualifies is now.

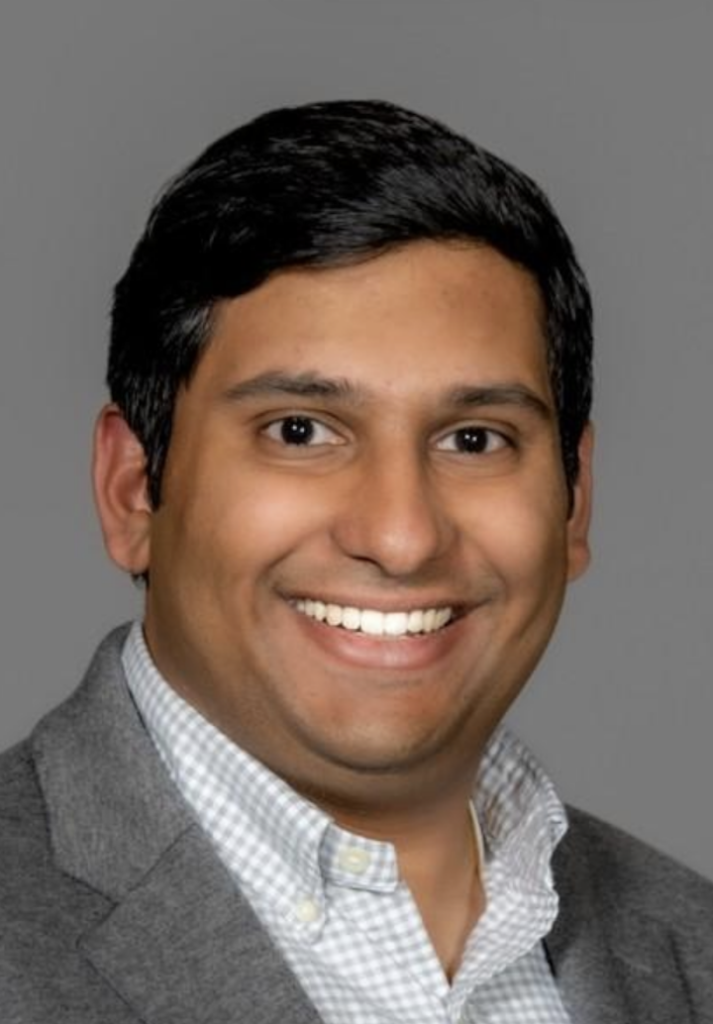
Abhishek Veeraghanta is founder/CEO of Pidgin.

Central Bank to Reduce Number of 2027 Meetings at Which it Votes on Rates

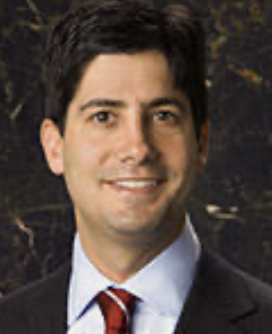
 WASHINGTON — Federal Reserve Chairman Kevin Warsh said the central bank will reduce the number of meetings at which it votes on interest rates beginning in 2027, setting aside more time to examine broader monetary policy questions.

The Federal Open Market Committee will continue meeting eight times annually, but only seven meetings next year will include an expected vote on the federal funds rate. In 2028, six meetings will be devoted to rate-setting and two to longer-term strategy, Warsh said at an Oct. 28 news conference.

Kevin Warsh
Kevin Warsh

“We believe eight meetings per year is the right number for the (Federal Open Market Committee), but in 2027, one meeting will focus exclusively on broad monetary policy strategy, with neither a vote on the federal funds rate nor a policy statement anticipated,” Warsh said, according to Reuters.

The Wall Street Journal reported that the change could give policymakers more time to assess economic conditions, but it could also delay routine responses to rapidly shifting inflation or employment trends.

A Break With Longstanding Practice

The Fed has held eight regularly scheduled policy meetings annually since 1981, during Paul Volcker’s chairmanship. The New York Times reported in July that Warsh had raised the possibility of reducing the frequency of rate-setting meetings as part of a broader effort to change how the Fed operates.

The central bank retains the ability to make emergency policy decisions between scheduled meetings, as it did during the onset of the COVID-19 pandemic.

Warsh said the strategy-focused sessions would allow policymakers to consider longer-term questions rather than concentrate exclusively on incoming economic data. He did not identify which 2027 meeting would be reserved for strategy or specify what public information would follow it, Reuters reported.

Rates Held Steady

The announcement followed the Fed’s decision to hold its benchmark interest rate steady at a range of 3.75% to 4%. Warsh, who became chairman in May, has also curtailed the length of policy statements and press conferences and avoided offering detailed guidance on future rate decisions.

Friday, October 30, 2026

NCOFCU's Online Director Advisor

NCOFCU Directors Advisor

The National Council of First Responder Credit Unions (NCOFCU) has introduced an exciting new membership benefit: the NCOFCU AI Directors Advisor.

Credit union directors, supervisory committee members, and CEOs face increasingly complex responsibilities. From regulatory compliance and financial oversight to lending, cybersecurity, and strategic planning, knowing the right questions to ask is essential to protecting and strengthening their credit unions. 

Members can ask questions in everyday language and receive clear, understandable explanations, practical guidance, and references to relevant regulations and educational resources.


Think of it as having a knowledgeable credit union governance and educational resource available whenever you need it — 24 hours a day, seven days a week.

What Does It Offer?

  • 24/7 educational assistance: Ask questions anytime, without waiting for a meeting or training session.

  • Easy-to-understand answers: Complex credit union subjects explained in plain English.

  • Governance and regulatory guidance: Explore NCUA regulations, board responsibilities, financial oversight, lending, BSA, cybersecurity, and succession planning.

  • Personal conversation history: Previous questions and discussions are saved for future reference.

  • Suggested follow-up questions: Discover additional issues and topics worth exploring.

  • Board meeting preparation: Better understand reports, policies, and management recommendations before making decisions.

  • Exclusive membership benefit: Available to authorized NCOFCU members through their secure member access.

The Advisor is an educational resource, not a replacement for legal, regulatory, or professional advice.

Give it a try NOW 


U.S. Economy Grew 3.4% in Q3, Driven by Consumer Spending, AI Investments

 WASHINGTON — The U.S. economy grew at a 3.4% annual rate in the third quarter, accelerating from 2.2% in the previous three months as consumer spending and business investment in artificial intelligence helped offset a widening trade drag, the Commerce Department reported Thursday.

A credit union economist said the data largely align with what the Federal Reserve said one day earlier in opting not to raise rates.

The advance estimate from the Bureau of Economic Analysis showed stronger growth from July through September than the 3% pace economists had forecast in a FactSet survey, according to The Associated Press. The report is the first of three estimates for the quarter.

Consumer Spending Increases

Consumer Spending Increases

Consumer spending increased at a 3.8% annual rate, while nonresidential business investment rose 12.7%, according to AP reporting on the government figures. Spending on information-processing equipment surged 37.4%, software investment rose 9.6% and research and development increased 7.5%.

The BEA said higher investment, household spending and government spending contributed to the expansion. Falling exports and rising imports partly offset those gains. Reuters reported Wednesday that imports of capital goods associated with AI infrastructure helped push the goods trade deficit higher in September.

Housing remained a weak point. Residential investment declined 3.3%, according to the AP, amid elevated mortgage rates.

America’s Credit Unions Economist Responds

“Economic growth came in stronger in the third quarter, with consumer spending and investment in AI continuing to be the biggest drivers. Domestic investment grew at its fastest pace since the beginning of last year. However, net exports significantly dragged on overall growth, as imports of goods tied to AI-related investment rose. Looking at September, the personal income and outlays report showed consumer spending slowing after accelerating earlier in the quarter. At the same time, the Fed’s preferred inflation measure rose notably during the month. These reports reinforce the Federal Reserve’s view that the economy remains on solid footing while price stability continues to be a concern,” said Dawit Kebede, senior economist at America’s Credit Unions.

Separate BEA figures released Thursday showed personal income rising 0.2% in September, while consumer spending increased 0.5% in current dollars, down from 0.9% in August. Inflation-adjusted consumer spending was essentially unchanged in September after increasing 0.5% in August.

The personal consumption expenditures price index, the Federal Reserve’s preferred inflation gauge, increased 0.5% in September and 3.6% from a year earlier, the BEA reported. Excluding food and energy, the index increased 0.3% for the month and 3.1% from a year earlier. Both annual measures remained above the Fed’s 2% inflation target.

The mixed reports underscore the challenge facing policymakers: Economic activity remains robust, but inflation is proving persistent. The BEA is scheduled to publish its second estimate of third-quarter GDP on Nov. 25.

Thursday, October 29, 2026

Fed Leaves Rates Unchanged; Sees Inflation but Also Strong Economic Activity

 WASHINGTON — As expected, the Federal Reserve left its benchmark interest rate unchanged Wednesday, keeping the target range at 3.75% to 4% as policymakers weighed strong economic activity against inflation that remains above the central bank’s 2% goal.

The Federal Open Market Committee voted 10-2 to hold rates following its two-day meeting, according to the Federal Reserve’s Oct. 28 statement. Federal Reserve Gov. Lisa Cook and Cleveland Fed President Beth Hammack dissented, favoring a quarter-percentage-point increase that would have raised the range to 4% to 4.25%.

The decision follows a unanimous quarter-point increase in September, when the Fed raised its target range to the current level. Wednesday’s split vote underscored disagreement over how quickly the central bank should move to curb persistent price pressures.

The decision follows a unanimous quarter-point increase in September, when the Fed raised its target range to the current level. Wednesday’s split vote underscored disagreement over how quickly the central bank should move to curb persistent price pressures.

America’s Credit Union Economist Responds

The FOMC’s decision to keep the federal funds rate target range unchanged gives policymakers room to see how September’s increase works through the economy while balancing elevated inflation and a softening labor market,’ Dawit Kebede, senior economist with America’s Credit Unions, said in a statement. “Although the economy remains strong and unemployment is low, the press release points to elevated uncertainty and the need for more information before another rate decision.  With underlying inflation still above the Fed’s target, today’s decision reads as a wait-and-see, and a December hike is more likely. Credit unions remain well positioned to help members manage the pressures of high prices and elevated rates.”

‘Growth is Solid’

In its statement, the Fed upgraded its description of economic growth from “solid” in September to “strong.” It cited resilient consumer and business spending, robust capital investment and productivity gains, while saying job growth has kept pace with the workforce and unemployment has changed little.

“Inflation remains elevated,” the committee said. It added that gathering more information would help determine the appropriate policy to return inflation to 2%, signaling that future rate decisions will depend on incoming economic data.

December Rate Increase Remains Possible

Reuters reported Wednesday that the Fed’s decision was widely anticipated and that investors continue to expect another rate increase, potentially beginning in December. Its reporting also pointed to concerns that inflationary pressures are spreading beyond energy costs.

A Reuters survey conducted Oct. 16-20 found that 94 of 100 economists expected the Fed to hold rates in October, while all 100 anticipated an increase in December. Those forecasts are expectations, not commitments by the Fed, which did not announce a December decision Wednesday.

Implications for Credit Unions and Borrowers

For credit unions, the decision leaves the Fed’s short-term rate benchmark unchanged for now, but continued uncertainty over the next move complicates loan pricing, deposit-rate decisions and interest-rate risk management. Institutions may still see market funding costs shift as expectations for December change.

The Fed’s next scheduled policy meeting is Dec. 8-9, when officials are also due to publish updated economic projections.

Tuesday, October 27, 2026

Early Voting Shifts


Early Voting Shifts


More than 30 million Americans have voted in this year's midterms so far, with Election Day one week away. In Texas, over 4 million ballots have been cast, exceeding half of the state's 2022 turnout. The figures are from the University of Florida's Election Lab; see how your state compares here.

Voting methods are also shifting, particularly in parts of the South. In Georgia, roughly 95% of early votes have been cast in person, while mail ballot requests have fallen more than 45% from 2022. North Carolina has seen a similar split, recording 1.5 million in-person votes and about 60,000 mail ballots returned. Nationally, early votes are roughly even between in-person (15.4 million) and mail (15.1 million) as of this writing.

Experts say the shift may reflect concerns about mail ballots arriving on time or being counted, as well as a return to prepandemic voting habits. A Postal Service rule in effect since December largely postmarks mail when it's processed rather than dropped off, potentially pushing some ballots past deadlines.

See the 52 races that could flip Congress here.

=====================================================================

Remember, you're not alone with NCOFCU.org / Join

Friday, October 23, 2026

Economic Mixed Signals


Economic Mixed Signals


US jobless claims fell to 194,000 last week, their lowest since July, according to Labor Department data released yesterday, indicating a stable labor market less than two weeks before the midterm elections.

Claims, a proxy for layoffs, have remained historically low this year, reaching a 57-year low in July. However, hiring has slowed—employers added just 29,000 jobs in September, and unemployment rose to 4.2%. The result is a “low-hire, low-fire” job market in which most workers keep their jobs while job seekers struggle to find work. The economy grew at a 2.2% annualized rate in the second quarter, while consumer spending, which drives roughly two-thirds of economic activity, rose 0.9% in August, outpacing income growth. Annual inflation reached 3.7% in September, up from 3.4% in August and above the Federal Reserve’s 2% goal.

A recent poll found 85% of voters consider the economy a top election issue, while 84% cited the cost of living. Explore five charts showing the US economy ahead of the midterms.


=====================================================================

Remember, you're not alone with NCOFCU.org / Join

SF Fire Credit Union celebrating 75th anniversary.


President and CEO at SF Fire Credit Union

1w

San Francisco Fleet Week Association at its heart is about bringing together the military, first responders, and the people they serve. That made it a meaningful backdrop for SF Fire Credit Union to continue celebrating our 75th anniversary and the firefighter community that inspired our founding in 1951.

We kicked off the week on October 6 with a ceremonial ribbon cutting at our Noe Valley branch alongside the San Francisco Chamber of Commerce, San Francisco Fire Department Chief Dean Crispen, Sam Gebler and SF Firefighters L798 members, Guardians of the City, San Francisco, marking 75 years of service and our continued commitment to the San Francisco community. We then joined K9 Heroes Day at Duboce Park on October 10 and spent October 11 at Fleet Fest at Pier 27.

I’m grateful we had the chance to celebrate this milestone in a way that felt true to who we are: rooted in service, connected to our community, and proud to stand alongside the people who show up for San Francisco every day. #FleetWeek


What the 2027 FedNow Discount Program Means to Credit Unions

  For credit unions that have been considering FedNow but have yet to move forward, the Federal Reserve has added a significant financial in...